Q3 drives 74% of Emirates NBD Egypt’s 9M-2026 profit growth
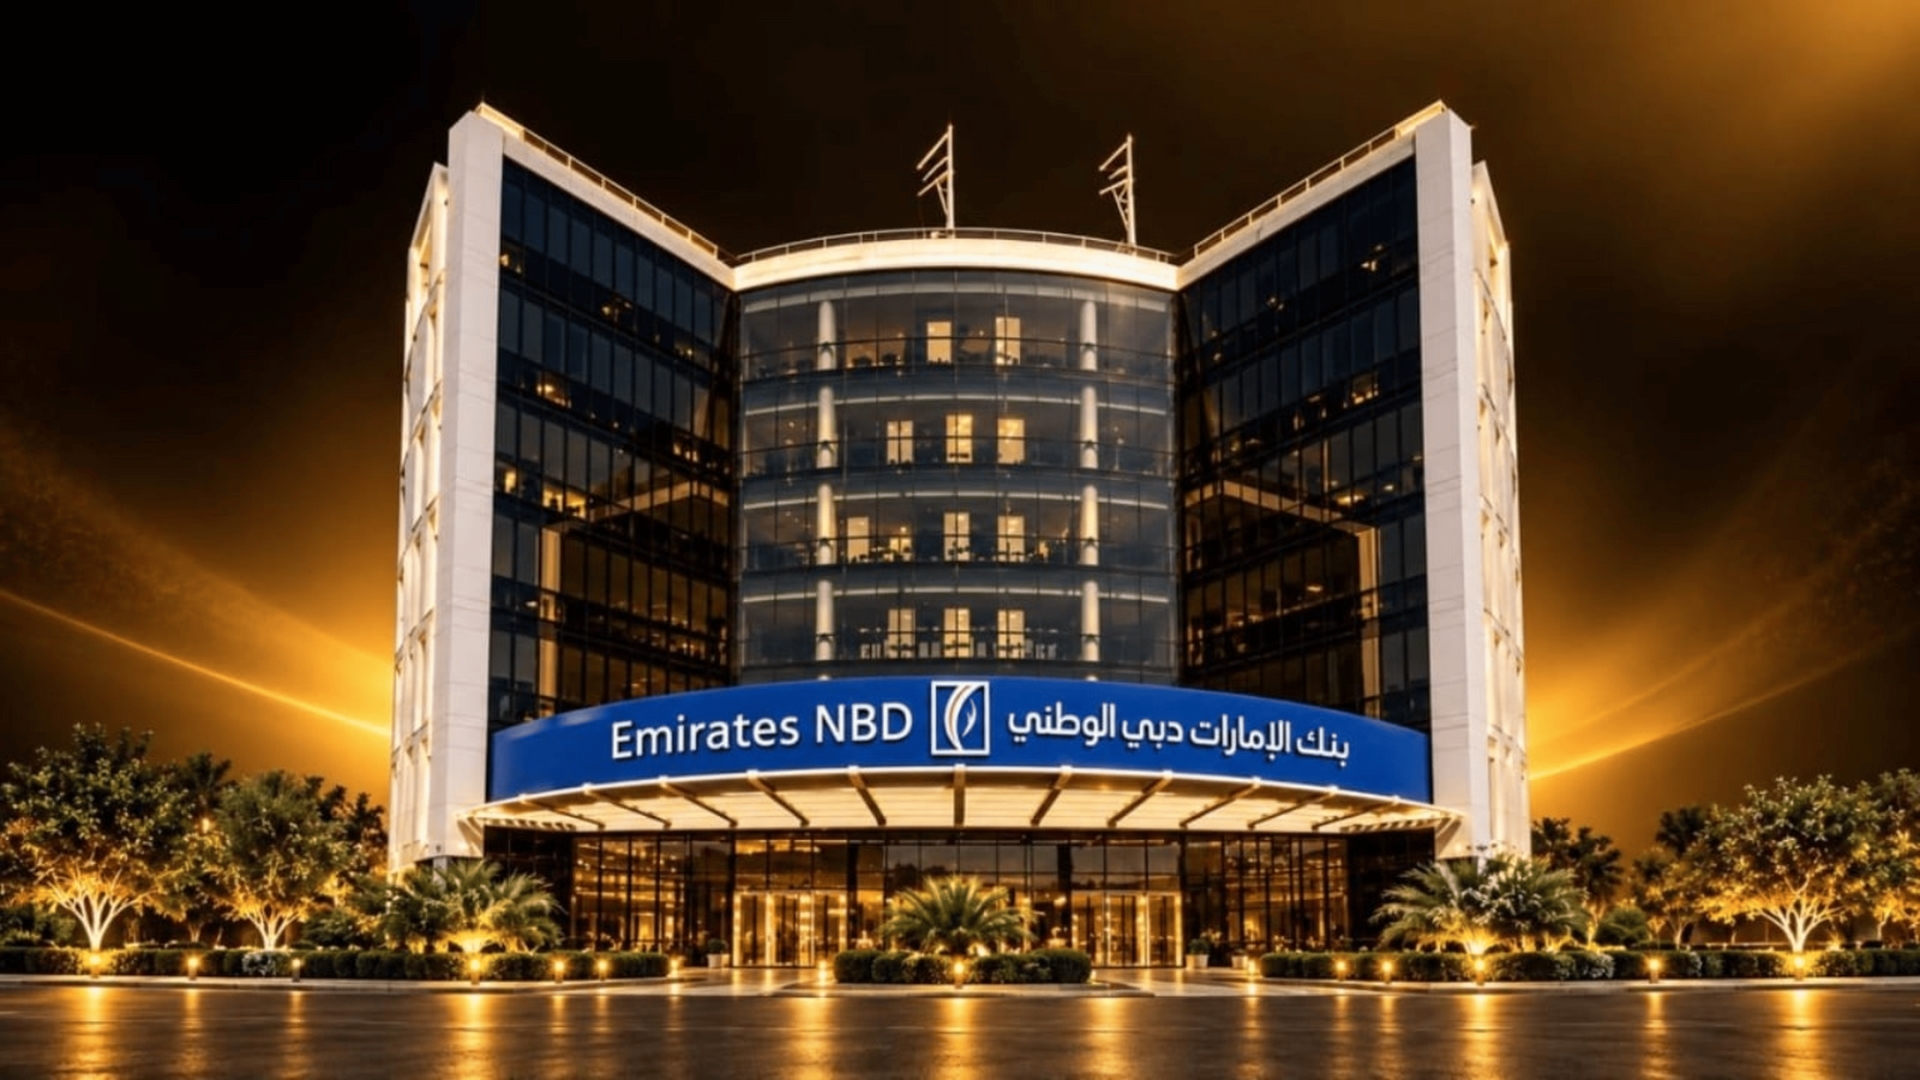
First Bank’s analysis of Emirates NBD Egypt’s financial statements revealed faster profit growth in Q3-2026, which alone accounted for around 74 per cent of the increase in the bank’s net profit during 9M-2026.
This performance was supported by growth in the bank’s main income sources, alongside a more favourable impact from impairment charges for credit losses on the income statement during the third quarter of 2026.
The bank’s net profit surged 62.9 per cent during Q3-2026, reaching EGP 2.14 bn, compared to EGP 1.31 bn in Q3-2025, representing an increase of EGP 827.29 mn year-on-year during the quarter.
This compares with a growth rate of 9.6 per cent during H1-2026, reflecting a notable acceleration in the bank’s profitability during the third quarter of the year compared with the first half.
This performance lifted the bank’s net profit by 25.8 per cent during 9M-2026, reaching EGP 5.45 bn, compared to EGP 4.33 bn in the corresponding period of 2025, year-on-year during the period.
Net profit therefore increased by approximately EGP 1.12 bn during the first nine months of 2026, with Q3 accounting for around 74 per cent of the total increase recorded over the period.
An analysis of profitability drivers shows that net interest income remained the main contributor to profit growth, alongside improved fee and commission income and lower impairment pressures during Q3-2026 overall.
These developments supported the bank’s profitability, despite increases in some expense items during the third quarter of the year, particularly across selected operating cost categories and income tax expenses during the reporting period.
Net interest income adds EGP 694 mn in Q3-2026
Net interest income continued to serve as a key driver of the bank’s profitability during Q3-2026, increasing by 21.1 per cent to EGP 3.99 bn, compared to EGP 3.29 bn in Q3-2025.
This represented an increase of approximately EGP 694.34 mn, reflecting the continued contribution of the bank’s core banking activity to its quarterly earnings growth during the third quarter of 2026.
The increase was driven by interest income growing at a faster pace than deposit and similar costs, supporting the expansion in net interest income during the third quarter of 2026.
Interest income rose 16.3 per cent during Q3-2026 to EGP 9.71 bn, compared to EGP 8.34 bn in Q3-2025, reflecting stronger returns from the bank’s interest-earning assets during the quarter.
Meanwhile, interest and similar expenses increased at a slower rate of 13.2 per cent, reaching EGP 5.72 bn, compared to EGP 5.05 bn in the corresponding quarter of 2025, respectively.
Q3 performance contributed to a 23 per cent increase in net interest income during 9M-2026, which reached EGP 11.54 bn, compared to EGP 9.38 bn in the corresponding period of 2025.
This represents an increase of approximately EGP 2.16 bn, reinforcing net interest income’s position as the bank’s main source of revenue growth during the first nine months of 2026 overall.
Net fee and commission income jumps more than 30%
Net fee and commission income recorded a notable improvement during Q3-2026, rising by 30.3 per cent to EGP 519.54 mn, compared to EGP 398.84 mn in Q3-2025, year-on-year during the quarter.
This performance marked a significant acceleration compared to the limited growth rate of 0.6 per cent recorded during H1-2026, indicating stronger momentum in fee-generating activities in the third quarter of 2026.
The improvement was supported by a 24.3 per cent increase in fee and commission income during Q3-2026, outpacing the 13.9 per cent growth in related expenses over the same period.
This difference supported the increase in net income generated from fee and commission activities, contributing to the bank’s stronger profitability during the third quarter of 2026 compared with the previous year.
Q3 performance lifted the growth rate of net fee and commission income to 9.5 per cent during 9M-2026, reaching EGP 1.44 bn, compared to EGP 1.32 bn in the corresponding period of 2025.
Improved impairment impact supports Q3 earnings
The change in impairment charges for credit losses was among the key factors supporting the bank’s profit growth during Q3-2026, as it recorded a positive impact of EGP 73.97 mn on the income statement.
This compares with an impairment charge of EGP 253.07 mn in Q3-2025, representing an improvement of EGP 327.04 mn in the impact of impairment on the income statement year-on-year.
Accordingly, impairment pressures declined during the third quarter, while the total impairment charge for credit losses fell by 26.3 per cent during 9M-2026 to EGP 757.07 mn overall during the reporting period.
This compares with EGP 1.03 bn in the corresponding period of 2025, reflecting a lower burden from impairment charges on the bank’s income statement during the first nine months of the year.
This development indicates easing pressure on the bank’s profitability, but does not necessarily point to an improvement in the quality of its credit portfolio or underlying credit risk within the bank.
Trading income and lower expenses support profitability
Net trading income increased by 19.4 per cent during Q3-2026, reaching EGP 218.38 mn, compared to EGP 182.94 mn in Q3-2025, an increase of EGP 35.45 mn year-on-year during the quarter.
Meanwhile, administrative expenses declined by 1.3 per cent to EGP 1.08 bn, compared to EGP 1.10 bn in Q3-2025, helping limit the rise in operating costs during the quarter under review.
Net other operating expenses also decreased by 12.5 per cent, reaching EGP 465.56 mn, compared to EGP 532.33 mn in the corresponding quarter of 2025, supporting quarterly profitability during the period under review.
These developments, alongside growth in the bank’s main income sources and the improved impact of impairment charges, supported a 62.8 per cent increase in profit before income tax during Q3-2026.
Profit before income tax reached EGP 3.26 bn during Q3-2026, compared to EGP 2 bn in Q3-2025, reflecting stronger operating performance during the third quarter of the year.
Despite a 62.5 per cent increase in income tax expenses to EGP 1.12 bn, compared to EGP 688.03 mn, the bank’s net profit rose by 62.9 per cent during Q3-2026.
A closer look at profitability drivers
The bank’s Q3-2026 results reflected a notable improvement in profit growth, supported by stronger income from core activities, faster growth in fee and commission income, and lower impairment pressures overall.
This performance points to a broader range of factors supporting profitability during the third quarter, despite continued increases in some expense items across the bank’s operations during the period under review.
Growth in income sources and cost management efficiency are therefore among the key factors expected to influence the bank’s financial performance in the coming periods, alongside asset quality developments.